






Why Trump Is Calling for 1% Interest Rates While the Federal Reserve Is Moving the Other Way

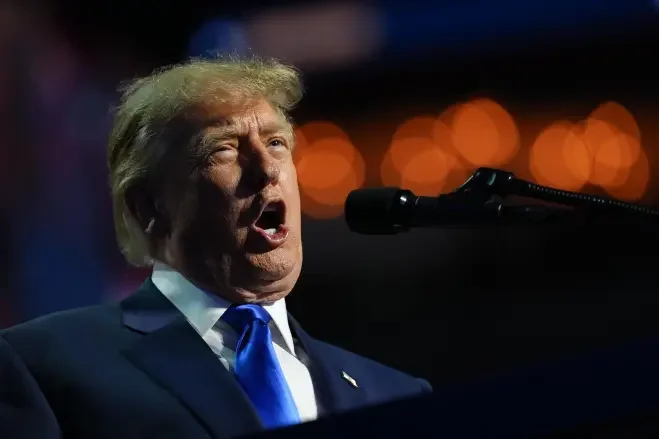
President Donald Trump is pushing for U.S. interest rates to fall to 1% or lower, but that demand is running into economic conditions that make such a sharp reduction difficult. Analysts say cutting the Federal Reserve’s policy rate from its current 3.75%–4% range to 1% could unsettle financial markets and potentially increase the government’s borrowing costs.
Trump has argued that the United States should enjoy exceptionally low rates because of its economic strength and credit standing. But inflation remains elevated, and the Federal Reserve has recently moved rates higher rather than lower. The disagreement highlights the gap between the president’s preferred borrowing costs and the central bank’s approach to inflation and monetary policy.
Trump’s 1% Demand and the Fed’s Recent Decision
Trump has repeatedly called for much lower interest rates, including in public comments and social media posts. After the Federal Reserve raised its benchmark rate last week, he again said rates should be reduced to 1% or less.
The Fed’s recent quarter-point increase brought its target range to 3.75%–4%, according to Reuters and Axios. The move was the first rate increase in more than three years, and it came as policymakers continued to confront persistent inflation.
Trump has also said the country should have the world’s lowest interest rates. In remarks reported by Reuters earlier this month, he argued that the United States should not be paying more than other countries to borrow.
Why Analysts Say a 1% Rate Could Create Problems
A central concern is that the Federal Reserve does not directly control every borrowing rate in the economy. Its policy rate influences short-term financing, but longer-term rates—including those affecting mortgages and government bonds—also respond to inflation expectations, investor demand and the supply of debt.
Reuters reported that analysts warned a rapid reduction to 1% could trigger significant disruption in global financial markets. Investors might demand higher yields if they expected the move to fuel inflation or undermine confidence in U.S. monetary policy.
That could create an unexpected result: even if the Fed cut its benchmark rate, the U.S. government could face higher borrowing costs in bond markets.
Inflation Is a Major Obstacle
Inflation is one of the main reasons the Fed’s policy direction differs from Trump’s stated preference.
Reuters reported that the Fed’s preferred inflation measure was 3.7% in July, while policymakers did not expect inflation to return to their 2% target before 2029. The report also described pressure from tariffs and higher energy costs linked to the war involving Iran.
The Associated Press has also reported that inflation remains stubborn even as the economy continues to grow. Analysts cited strong consumer spending, investment in artificial-intelligence infrastructure and large federal budget deficits as factors contributing to higher interest rates.
Lower interest rates can make borrowing cheaper and support economic activity, but cutting rates while inflation remains high can also risk adding to price pressures. That tension is central to the debate over how quickly monetary policy should change.
The Bond Market Matters Beyond the Fed’s Benchmark Rate
The administration’s preferred rate is not the only number that affects households and businesses.
Mortgage rates and other longer-term borrowing costs are shaped partly by Treasury yields and investor expectations. The AP reported that the average 30-year mortgage rate had climbed to 6.95%, while 10-year Treasury yields had moved above 5%.
Those figures illustrate why a change in the Fed’s benchmark rate does not automatically translate into an equivalent change in mortgage or other long-term rates.
If investors became concerned that a sharp rate cut would increase inflation or weaken confidence in the dollar, longer-term yields could move higher rather than fall, analysts told Reuters.
Trump’s Relationship With Fed Chair Kevin Warsh
Trump’s criticism of interest-rate policy has also raised questions about the relationship between the White House and the Federal Reserve.
Reuters reported that Trump has generally directed his recent public criticism toward the Fed’s policymakers, while speaking more favourably about Kevin Warsh, the chair he selected. After the latest rate increase, Trump said he had told Warsh to go along with the board if necessary.
Warsh has maintained that the Fed will pursue price stability. Following the September decision, Apollo Global chief economist Torsten Slok said the rate increase demonstrated that Warsh was serious about that commitment.
The Wall Street Journal reported that Warsh has sought to maintain a cooperative relationship with the White House while preserving the central bank’s independence. The relationship could face further pressure if the Fed raises rates again before the November midterm elections.
Affordability and the Midterm Election Debate
Interest rates have become part of the broader political debate over the cost of living.
Higher mortgage rates can make home purchases more expensive, while elevated prices for everyday goods can put pressure on household budgets. Reuters reported that affordability concerns are weighing on the political environment ahead of the November midterms.
The same report cited a Reuters/Ipsos poll in which 17% of respondents approved of Trump’s handling of the cost of living. That is a specific poll finding, not a measure of every voter’s views, but it indicates the political sensitivity of prices and borrowing costs.
Trump has presented lower rates as a way to support the economy and reduce borrowing costs. Critics and some analysts, however, argue that rate policy must also account for inflation and the consequences of market expectations.
What Happens Next?
The Fed’s future decisions will depend on economic conditions, including inflation and growth, rather than solely on the president’s preferred rate. Reuters reported that markets had begun to price in the possibility of another increase, while Fed projections also pointed to the risk of rates staying higher for longer.
That leaves a clear divide between Trump’s call for rates at 1% or below and the central bank’s current focus on inflation. Whether borrowing costs eventually decline will depend on how the economic data develops and how policymakers assess the balance between price stability and economic activity.
For now, the president’s demand is a political and economic pressure point—but it is not a rate decision. The Federal Reserve’s policy choices, along with bond-market responses, will determine how borrowing costs evolve.

